Business · India Bureau
Asian Paints faces margin headwinds despite Q2 revenue beat
Asian Paints delivered stronger-than-expected revenue growth in the second quarter of fiscal 2027, but analysts warn that mounting raw material costs and competitive pressures may constrain profit margins going forward. Crude oil price volatility poses an additional risk to the paint manufacturer's profitability outlook.
LSN India ·
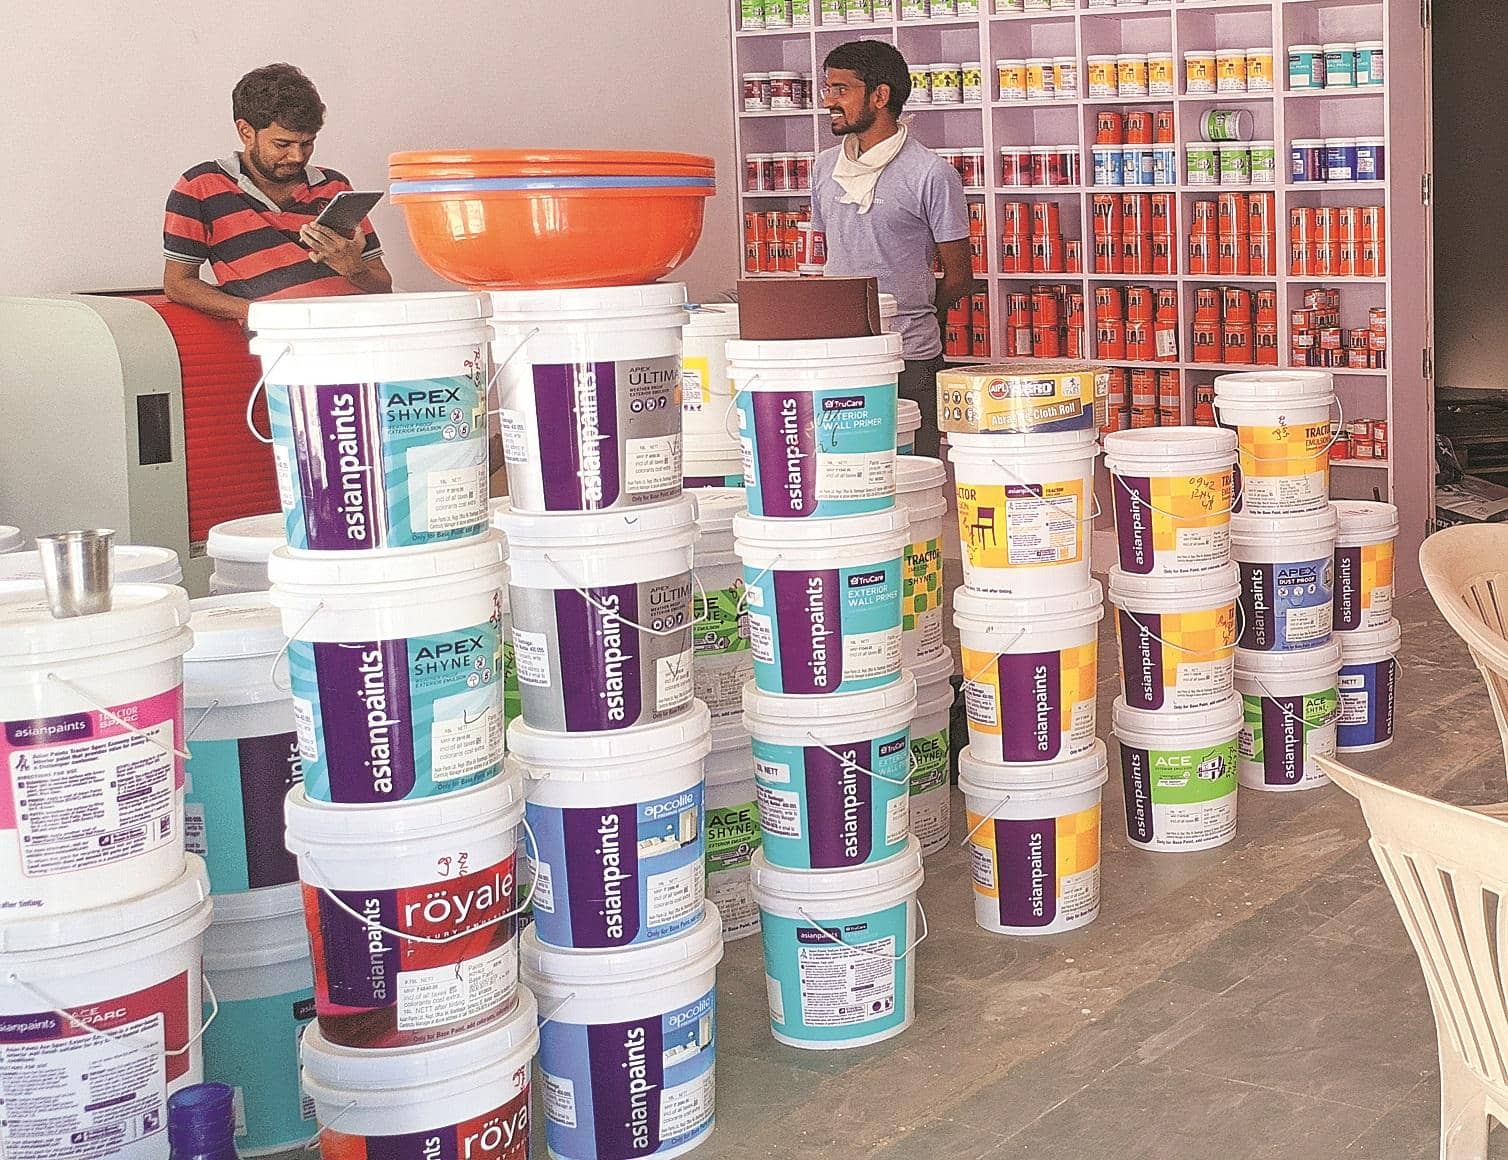
Asian Paints exceeded revenue growth expectations in Q2FY27, signalling solid demand across its core markets. However, the company's bottom-line performance remains under pressure from a combination of structural and cyclical headwinds that have begun to overshadow top-line gains.
Rising raw material costs continue to erode profitability, with crude oil—a key input for paint production—experiencing significant price swings. The volatility in commodity markets has made it difficult for manufacturers to pass through cost increases to consumers without risking volume losses in an increasingly competitive environment.
Intensified competition in the decorative and industrial paint segments has further squeezed margins, limiting the company's pricing flexibility. Rivals across the region are vying for market share through aggressive promotional strategies, forcing established players to balance growth ambitions against margin preservation.
Investors have grown cautious about Asian Paints' near-term stock performance amid these headwinds. While the company's revenue resilience demonstrates underlying business strength, margin compression may limit upside for equity holders until commodity costs stabilise or competitive dynamics ease.
Analysts recommend monitoring the company's quarterly results for any changes in raw material inflation, pricing actions, and demand trends that could signal whether margin pressures will persist or gradually abate in coming quarters.