Business · Singapore Bureau
Singapore home buyers boost cash, CPF contributions amid rising mortgage values
Property purchasers in Singapore are increasingly deploying larger down payments from personal savings and CPF funds despite the growth in million-dollar mortgages, according to banking sector observations. The trend suggests buyers are maintaining financial caution even as property valuations climb.
LSN Singapore ·
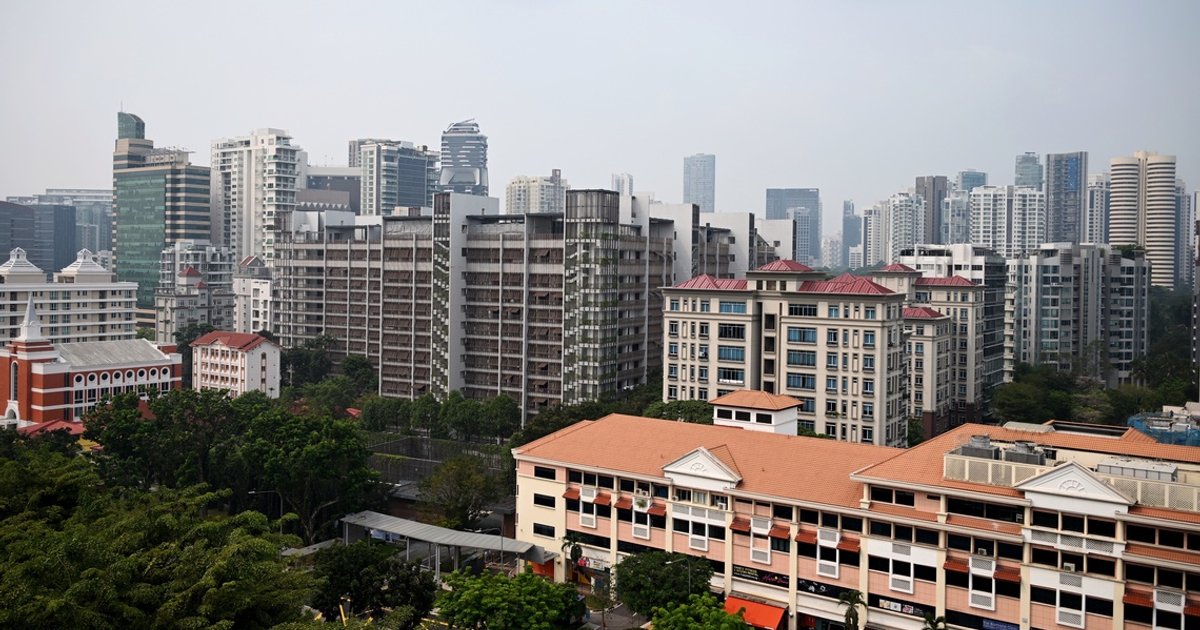
Singapore's residential property market is witnessing a notable shift in buyer behaviour, with homeowners putting down larger cash and Central Provident Fund contributions to secure their purchases, even as the quantum of mortgage loans continues to grow.
Financial institutions have reported a steady increase in the number of mortgages exceeding S$1 million, reflecting the sustained elevation of property prices across the island. However, this expansion in lending volumes has been accompanied by a parallel increase in down payment amounts from buyers, suggesting a cautious approach to leverage.
Bankers have noted that borrowers across income segments remain financially disciplined, with many electing to deploy additional equity from their CPF accounts and personal reserves rather than maximising their borrowing capacity. This pattern indicates that despite the ability to access higher loan amounts, buyers are prioritising financial buffers and reduced debt servicing obligations.
The behaviour reflects broader economic resilience among Singapore's property-buying demographic, with households maintaining sufficient liquid and retirement savings to weather potential interest rate volatility. Banking analysts attribute the trend partly to heightened awareness of debt sustainability and partly to the relatively strong financial position of property market participants.
The dual movement—rising mortgage volumes paired with elevated down payments—underscores a market in which growing property values are driving higher absolute loan amounts, yet prudent borrowers continue to prioritise balance sheet strength over maximum leverage.