Politics · India Bureau
Supreme Court clarifies inherited gold must still justify tax origins
The Supreme Court has ruled that statutory exemption limits for inherited gold do not automatically shield families from tax scrutiny over the jewellery's source and valuation.
LSN India ·
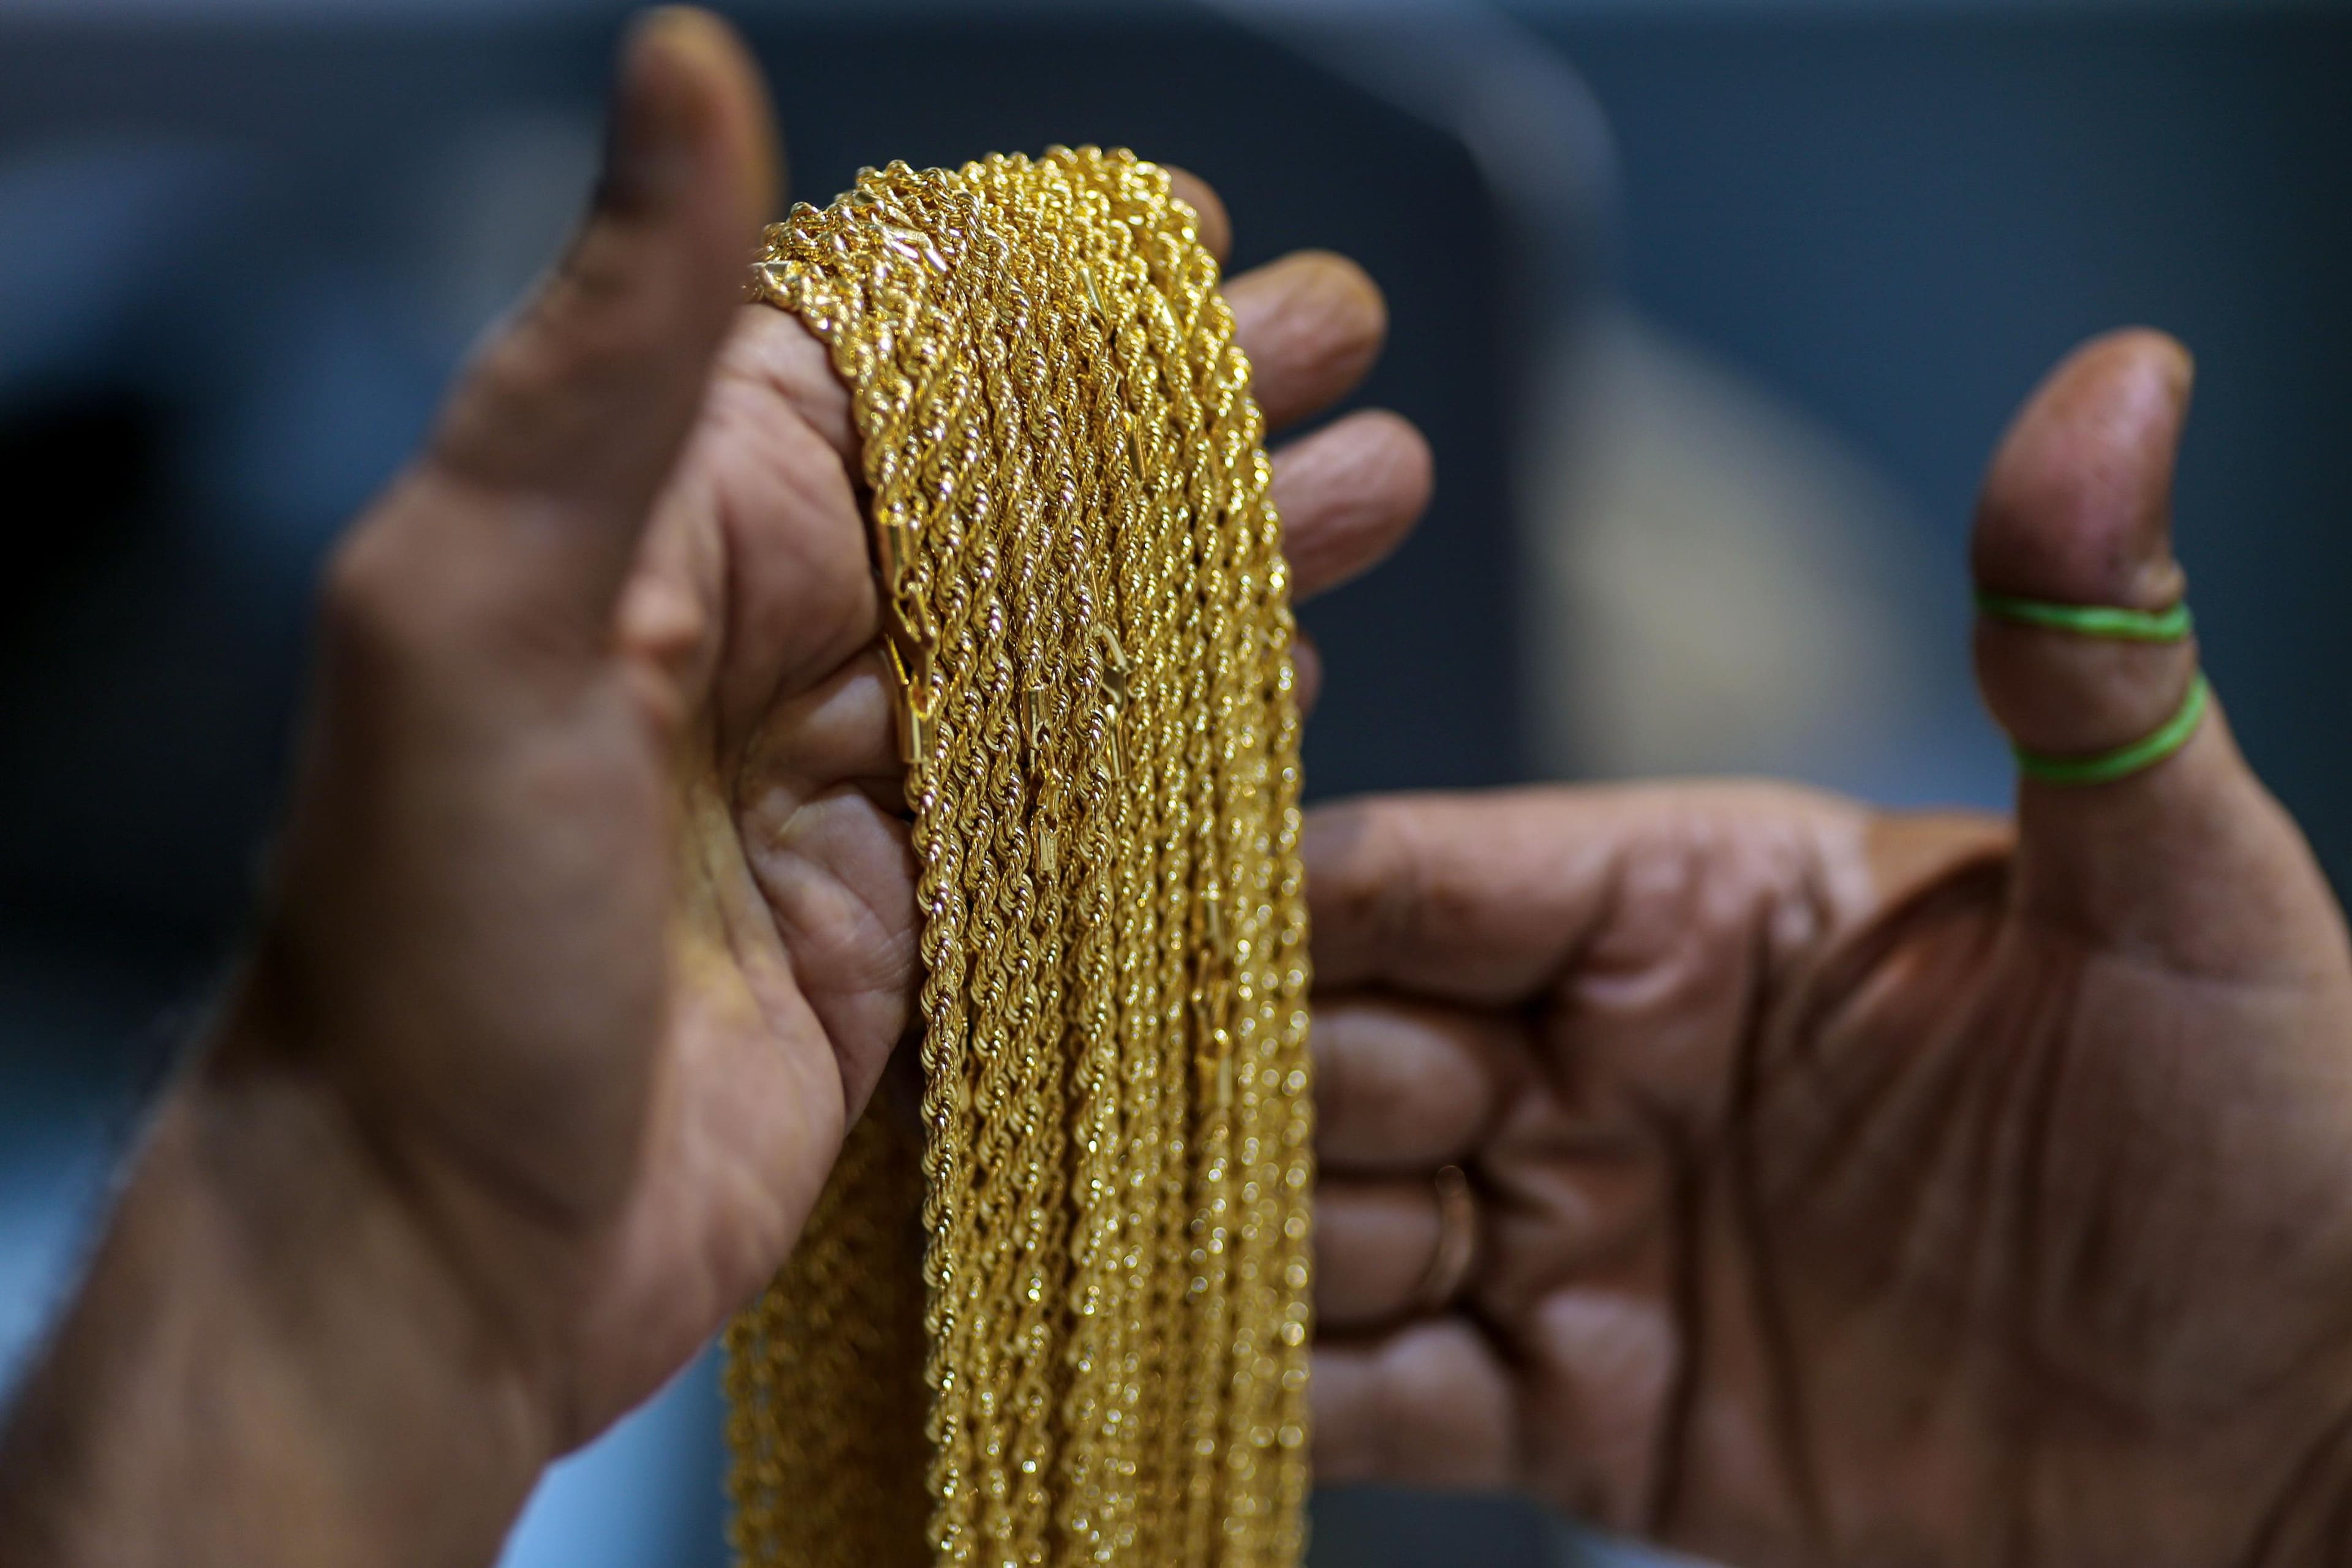
In a significant tax ruling, the Supreme Court has clarified that the absence of purchase bills for inherited gold does not provide a blanket exemption from tax authorities' investigation into its origins and value. The judgment addresses a common misconception among taxpayers regarding inherited jewellery and its treatment under tax law.
The court's order pertains to prescribed exemption limits—currently 500 grams for married women, 250 grams for unmarried women, and 100 grams for men—under the Wealth Tax Act and related provisions. While these thresholds historically provided some relief, the ruling establishes that merely falling within these limits does not absolve families of the responsibility to demonstrate the legitimate source and fair market value of inherited ornaments.
Tax authorities retain the power to examine inherited jewellery holdings beyond these limits, particularly when documentary evidence of the asset's origin or valuation is unavailable. The judgment reinforces that inherited assets must still satisfy documentation and valuation requirements during tax assessments, irrespective of exemption ceilings.
The ruling carries implications for wealth declaration and inheritance taxation across India. Families inheriting substantial gold jewellery are advised to maintain or reconstruct records evidencing the source and approximate valuation of such assets. Reliance solely on exemption thresholds without supporting documentation could invite tax department scrutiny and potential penalties during assessments.