Business · India Bureau
Tata Steel's Valuation Discount Unjustified, HSBC Maintains Buy Rating
HSBC has reiterated its bullish stance on Tata Steel, arguing that the company's current valuation discount relative to peers is not warranted. The international brokerage has retained its buy rating on the steelmaker.
LSN India ·
Tata Steel is trading at a significant discount to its peers despite fundamentals that do not justify such a valuation gap, according to HSBC's latest analysis. The company's one-year forward enterprise value to EBITDA multiple currently trades at a 14% discount to JSW Steel and a 3% discount to Jindal Steel, while commanding a 28% premium over Steel Authority of India.
The valuation disparity suggests the market may be underpricing Tata Steel relative to comparable players in the Indian steel sector. HSBC has maintained its buy recommendation on the stock, signaling confidence in the company's prospects despite the wider market sentiment that has weighed on its share price.
The brokerage's continued backing reflects expectations that Tata Steel's operational performance and growth trajectory will eventually be recognized by investors, potentially narrowing the valuation gap with peers. The rating retention comes as India's steel sector navigates fluctuating demand conditions and evolving global market dynamics.
HSBC's assessment suggests that current market valuations present a potential opportunity for investors, with Tata Steel positioned to capture value as conditions stabilize across the domestic steel industry.
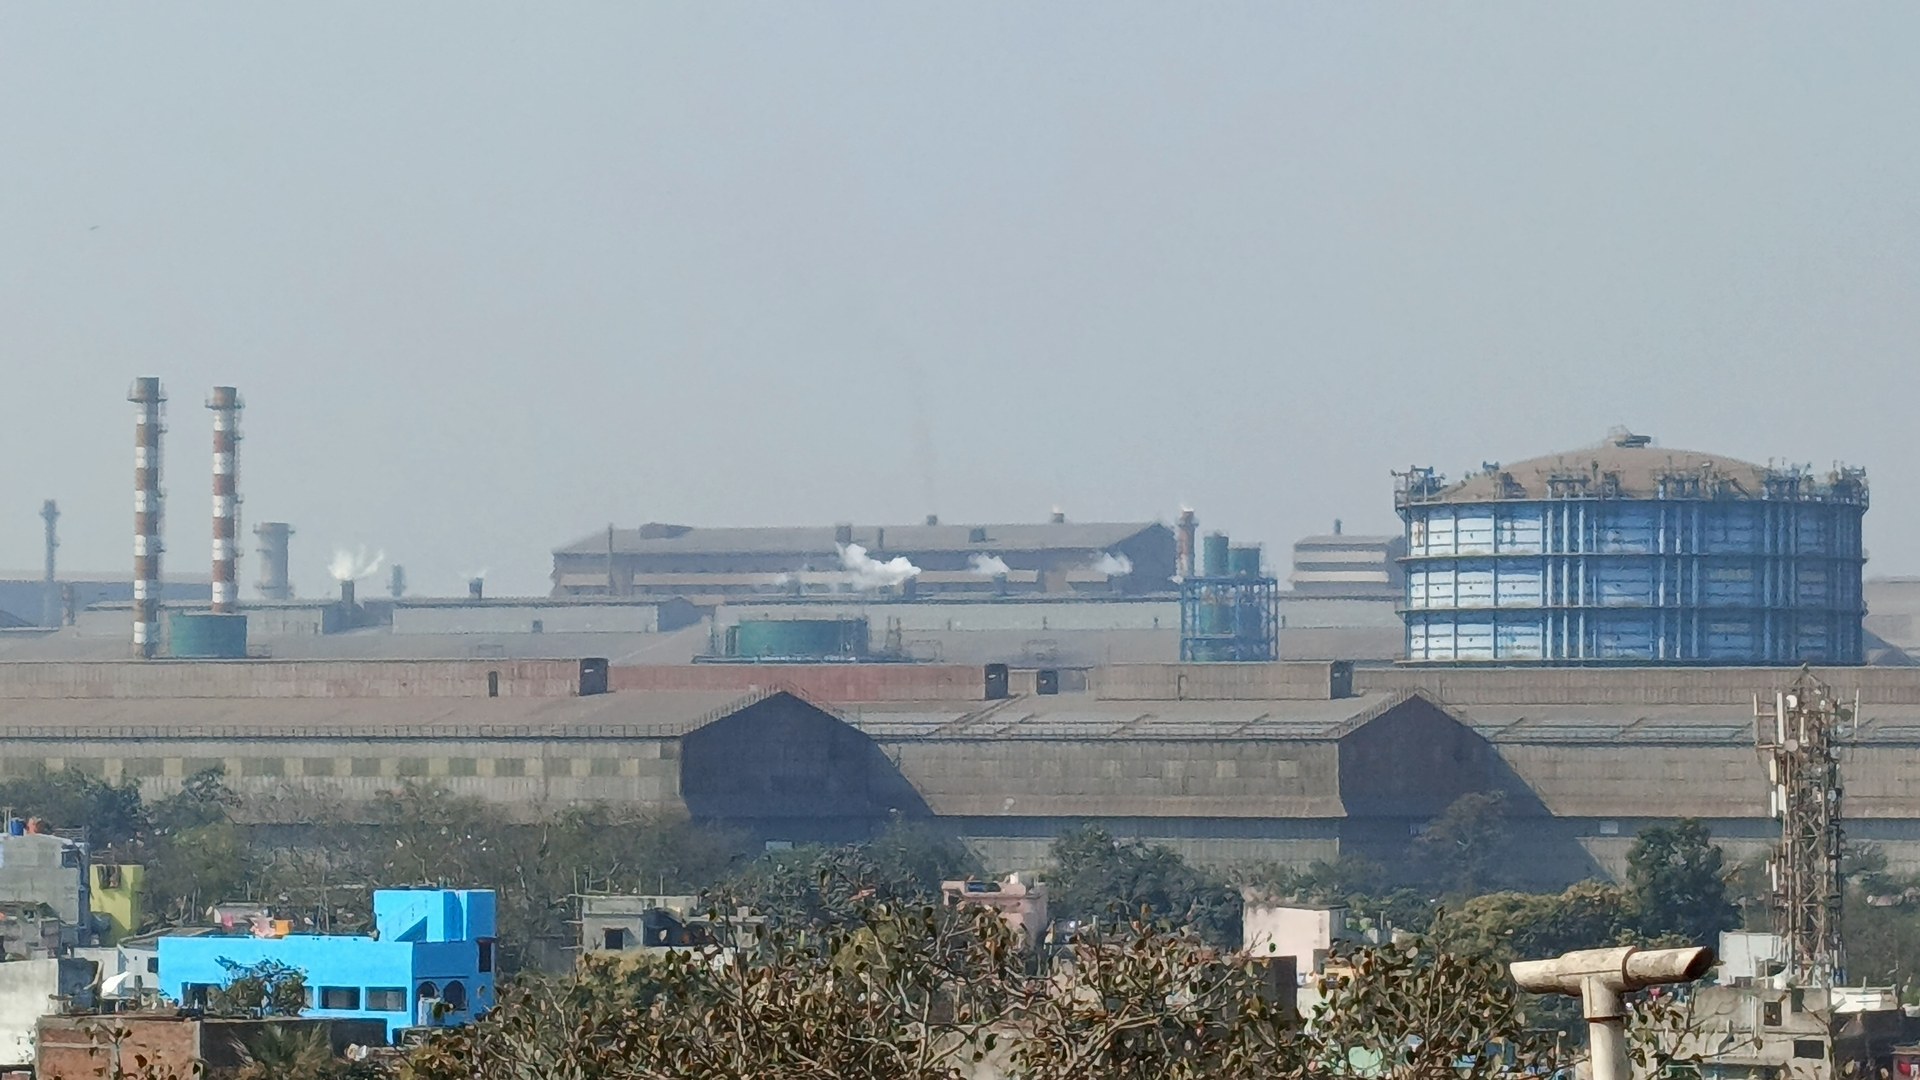
Photo: Tata Steel's works in Jamshedpur, Jharkhand, February 2026. Kharbaan Ghaltaan via Wikimedia Commons (CC BY-SA 4.0).