Politics · Vietnam Bureau
Vietnam's cross-border QR payment adoption lags despite infrastructure gains
While Vietnam has expanded its digital payment infrastructure significantly, adoption of cross-border QR payment systems remains limited, with only 6% of merchant locations currently accepting VietQR Global transactions.
LSN Vietnam ·
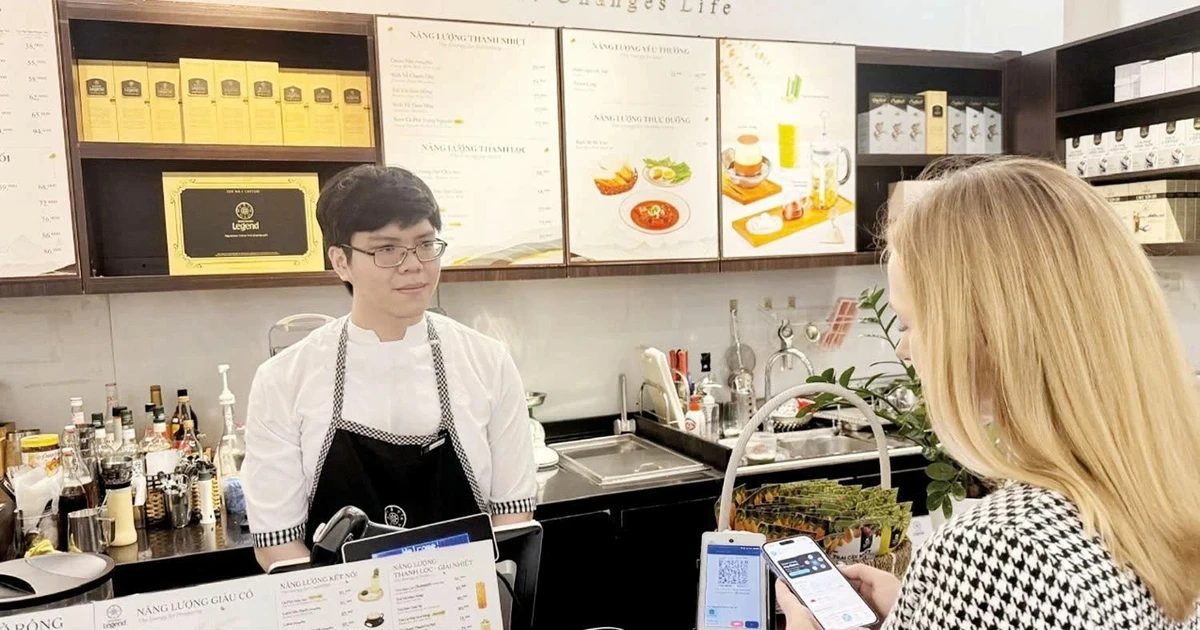
Vietnam's payment ecosystem has grown substantially, with the State Bank of Vietnam's Payment Department reporting more than 2.5 million domestic payment-accepting units nationwide. However, this expansion has not translated evenly across all payment technologies, particularly in the cross-border segment.
Data shows that approximately 154,000 merchants—representing just over 6% of total payment-accepting units—currently support VietQR Global, the country's cross-border QR code payment standard. This gap highlights a significant challenge as regional economies increasingly integrate their digital payment infrastructure to facilitate seamless transactions across borders.
The disparity suggests that expanding merchant coverage alone is insufficient to drive adoption of cross-border payment systems. Experts point to the need for coordinated efforts among stakeholders, including financial institutions, payment service providers, and government regulators, to address underlying barriers such as interoperability standards, merchant incentives, and consumer awareness.
Vietnam's position within ASEAN's broader digital economy framework makes this issue particularly relevant. Neighboring countries have established similar cross-border payment initiatives, and Vietnam's progress in this area will determine its competitiveness in the region's increasingly interconnected payment landscape.
Central bank officials have emphasized the importance of accelerating digital transformation and cashless payment adoption as part of the country's economic development strategy, signaling continued focus on closing the gap between domestic and cross-border payment infrastructure.